The Commercial Satellite Insurance Crisis: Shrinking Underwriter Pools
The commercial satellite industry is expanding rapidly, but the insurance market supporting it faces a difficult challenge: finding enough insurers willing to take on the financial risks of putting expensive technology into space. Satellite operators need protection against launch failures, equipment malfunctions, collisions, space debris and other unexpected events. However, major insurance losses, changing technology and cautious underwriting have made this specialised market increasingly selective.
Although insurance capacity has begun recovering from previous losses, the number of insurers prepared to accept difficult or unfamiliar satellite risks remains a concern. The result is a market where established satellite operators may find competitive insurance options while companies launching new technology face higher premiums, stricter conditions and fewer willing underwriters.
Source: WTW – Insurance Marketplace Realities 2027: Aviation and Space.

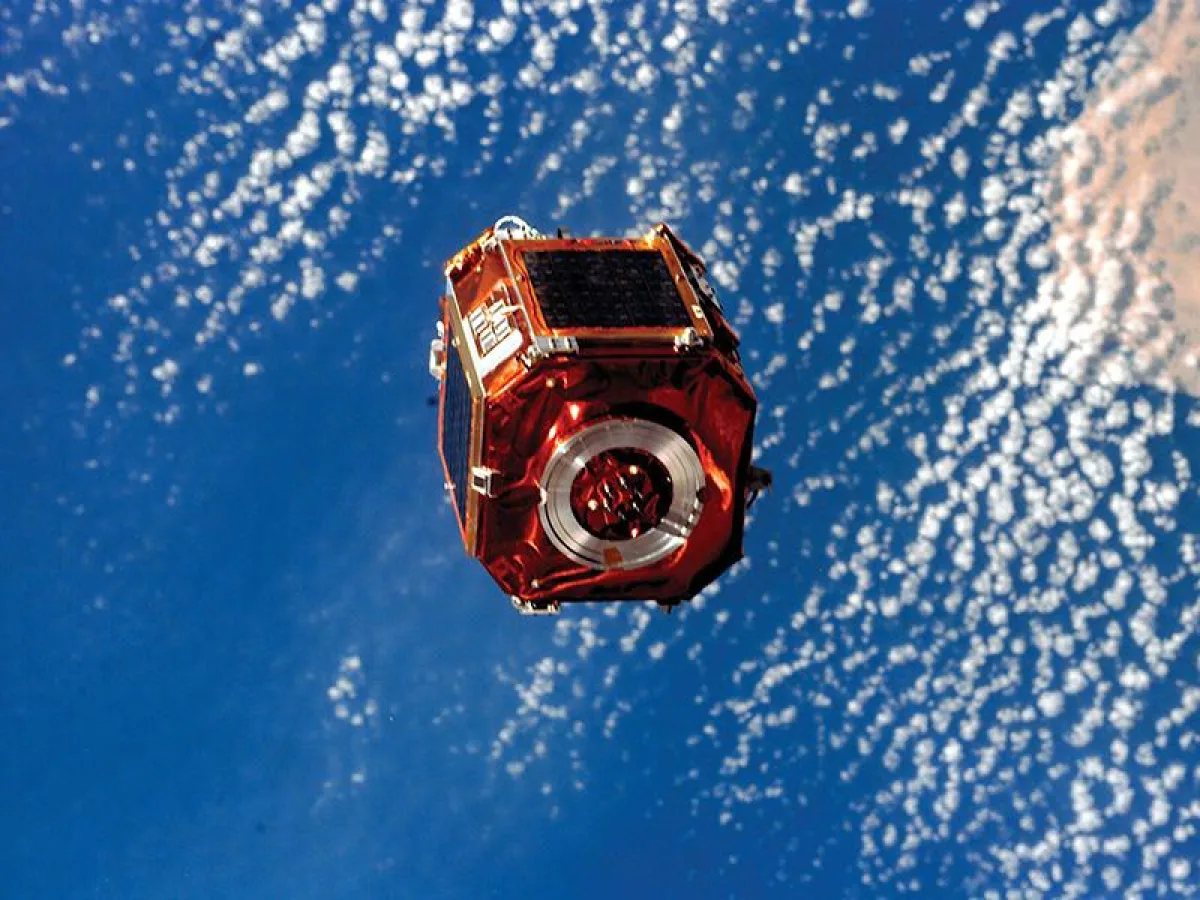
Illustrative image: A commercial satellite operating above Earth.
Understanding the Commercial Satellite Insurance Market
Satellite insurance is a specialised financial service that protects companies, governments and other organisations against losses associated with space activities. Policies can cover satellites during transportation, manufacturing, launch, early orbital testing and commercial operation.
The coverage is important because satellites can cost hundreds of millions of dollars to manufacture and launch. A serious failure can destroy years of investment, interrupt communication services and create significant financial problems for the operator.
According to Lloyd's of London, its specialist space insurance market has provided satellite coverage since 1965. Today, its underwriters support different stages of satellite operations, from manufacturing and launch to in-orbit commercial activities.
Source: Lloyd's – Space Risk and Satellite Insurance.
Why Are Satellite Insurance Underwriters Becoming More Cautious?
One of the biggest reasons behind the insurance market's difficulties is the financial impact of major satellite losses.
Space insurance operates differently from many ordinary insurance businesses. A relatively small number of expensive claims can consume a substantial portion of the premiums collected across the market. This makes insurers particularly sensitive to unexpected failures.
The situation became especially difficult following significant losses during 2023 and 2024. WTW's insurance market analysis documented approximately $1 billion in space insurance claims during 2023, followed by substantial additional claims in 2024.
These losses encouraged insurers to reconsider their exposure, increase premiums and become more selective about the satellite projects they were prepared to insure.
Source: WTW – Insurance Marketplace Realities 2025: Aviation and Space.
Another major setback came in December 2025, when Spain's SpainSat NG-2 satellite suffered a total loss following an apparent space-particle impact. Gallagher Specialty reported that the satellite was insured for more than $400 million. The incident significantly affected the market's expected underwriting performance.
A single incident of this scale demonstrates why satellite insurers cannot simply increase the number of policies they issue without carefully examining the potential financial consequences.
Source: Gallagher Specialty – Space Insurance Market Update Q1 2026.
The Shrinking Pool of Willing Underwriters
The reduction in available underwriting support has become a significant concern for satellite operators.
Several established insurance participants have reduced their involvement or withdrawn from the space insurance business in recent years. The departures of major market participants, including certain Hiscox, Canopius and Munich Re operations, contributed to the pressure on available capacity.
However, the market has also attracted replacement capacity. Former underwriting teams have established new operations, while other insurers have explored opportunities in specialist space coverage.
The important distinction is that total available insurance capacity and the number of insurers willing to accept particular risks are not necessarily the same thing.
A satellite with a successful operating history may attract several competing insurers. A newly developed spacecraft using unproven technology may struggle to obtain comparable support, even when its owners are prepared to pay higher premiums.
Source: The Insurer – Space Market Turns Corner as Significant Proportion of Capacity Replaced.
Why New Satellite Technology Creates Additional Insurance Risks
The growing use of smaller satellites and large low-Earth-orbit constellations is changing the economics of the satellite insurance industry.
Traditional commercial satellites are often extremely expensive individual assets. Newer satellite systems may consist of hundreds or thousands of smaller spacecraft designed to work together.
Although this approach can reduce dependence on individual satellites, it introduces different insurance challenges. Insurers must evaluate the possibility of multiple failures, technological weaknesses, collisions, operational disruptions and other risks affecting an entire constellation.
Furthermore, many newer satellite operators choose to self-insure their equipment or purchase limited coverage instead of insuring every satellite individually.
A report published by Business Insurance in October 2025 highlighted the difference between increasing satellite launch numbers and the slower growth of insurance purchases. The number of launches has increased substantially, but insurance demand has not grown at the same pace.
Source: Business Insurance – Satellite Launches Up, Insurance Take-Up Down.

Illustrative image: A network of small satellites operating in low Earth orbit.
The Financial Impact on Satellite Operators
When fewer insurers are prepared to accept a particular risk, satellite operators can face several financial disadvantages.
First, insurance premiums may increase, particularly for spacecraft with limited operating history. Second, companies may have to accept higher deductibles, reduced coverage limits or additional policy exclusions.
Third, obtaining insurance can become a longer process because underwriters require more technical information before making decisions.
This can affect smaller space companies more severely than established operators. Large organisations may have the financial resources to retain some risks themselves, while startups often depend on external insurance to satisfy investors, lenders, customers and regulatory requirements.
Gallagher's 2026 market assessment also highlighted the importance of proven launch vehicles. Insurers generally show greater confidence in established launch systems with successful operating histories than in vehicles with limited flight experience.
Source: Gallagher Specialty – Space Insurance Market Update Q3 2026.
Is the Satellite Insurance Market Recovering?
Despite the challenges, the satellite insurance industry is not experiencing a complete collapse.
There have been signs of recovery, with new underwriting capacity entering the market and insurers competing more actively for established satellite risks.
Gallagher's October 2026 assessment explained that competition remains stronger for proven launch vehicles and established technologies. However, newer launch systems still face difficulties because underwriters want evidence of reliability before committing substantial insurance capacity.
WTW's October 2026 market commentary similarly described a market with available capacity and relatively stable pricing, but increasingly detailed assessments of individual risks.
This suggests that the current challenge is not simply a shortage of money. It is also a shortage of risk appetite among insurers for certain types of satellite projects.
Sources: Gallagher Specialty – Space Insurance Market Update Q3 2026 | WTW – Global Insurance Marketplace Insights Q3 2026.

Illustrative image: A ground station supporting satellite communication and tracking.
What Does the Future Hold for Commercial Satellite Insurance?
The future of satellite insurance will depend on whether insurers can balance technological development with sustainable underwriting practices.
More reliable launch vehicles, improved spacecraft redundancy, better testing procedures and stronger operational data could encourage insurers to support a wider range of satellite projects.
There may also be opportunities to develop new insurance products for satellite constellations, smaller spacecraft and emerging commercial space infrastructure.
However, the industry must address the financial consequences of major claims. If another expensive satellite failure occurs, insurers could once again reconsider their participation and pricing strategies.
For satellite operators, the most important lesson is to consider insurance early in the development process rather than treating it as something to arrange immediately before launch.
Source: Gallagher Specialty – Space Insurance Market Update Q3 2026.
Conclusion
The commercial satellite insurance market is entering a period where technological progress is moving faster than insurers' willingness to accept unfamiliar risks.
Although underwriting capacity has improved following previous market losses, the industry still faces important challenges involving expensive claims, emerging technologies and uneven insurance demand.
The shrinking pool of willing underwriters does not mean commercial satellite insurance is disappearing. Instead, it highlights a growing difference between the risks insurers are comfortable accepting and the risks satellite operators increasingly need to transfer.
The companies that can demonstrate reliable technology, strong risk management and proven operational performance are likely to have an advantage when negotiating future insurance agreements.
Source: WTW – Insurance Marketplace Realities 2027: Aviation and Space.